Last month, the Federal Reserve raised its target range for short-term interest rates to 3.75% to 4%. The 0.25% rate hike was the Fed’s first increase in more than three years.
Long-term rates have climbed even faster. The 10-year U.S. Treasury yield jumped from about 4.8% to above 5% in about a month.
Higher rates make mortgages, business loans, and other financing more expensive. So many see rising yields as a threat to the economy.
They’re right to get worried to an extent. That said, knowing how and why rates rise is equally important. Right now, the bond market is sending a healthy signal.
The signal comes from the “yield curve,” the gap between what the government pays to borrow long term compared with short term. The difference between the 10-year Treasury yield and three-month Treasury yield is used to track the yield curve.
Normally, the 10-year pays more. Investors want extra return for tying up their money longer. And when the gap widens, the curve is “steepening.”
When short-term rates climb above long-term rates, the curve “inverts.” An inverted curve has been one of the most reliable recession warnings for decades.
That said, steepening can be a warning sign, too.
Before each of the past three recessions, the curve steepened sharply.
Short-term yields fell much faster than long-term yields so the gap widened. That’s because the Fed was slashing short-term rates as the economy weakened.
Said simply, a steeper curve meant the Fed was already trying to rescue a struggling economy.
Today, the opposite is happening.
Short-term rates have edged higher following the Fed’s hike. Long-term rates have risen even faster. The gap between 10-year and three-month yields recently topped 1 percentage point for the first time since mid-2022.
That’s a great sign for banks and the companies that borrow from these institutions.
Banks make money through short-term borrowing and long-term lending. The wider the gap between those two rates, the more a bank earns on every loan.
As a result, a steeper curve gives banks a reason to lend more.
Commercial and industrial (C&I) loans—the money banks lend businesses to buy equipment, stock up on inventory, and expand—are up 9.7% year over year. Bank loans to nonbank lenders, like private-credit funds, which then lend that money to businesses, are up roughly 20%.
So if higher rates were starting to choke off the economy, it would show up in lending first. Yet that’s not happening.
Instead, lending is speeding up.
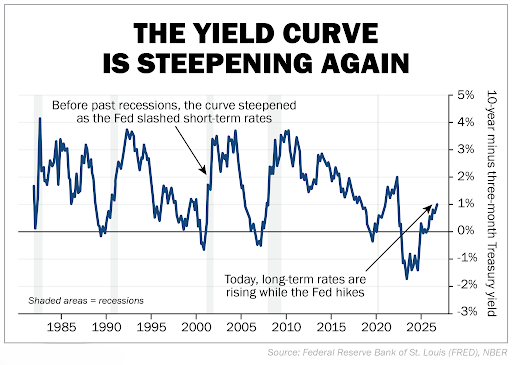
This time, the curve is steepening from the 10-year rate while the Fed is still hiking.
Long-term rates are rising because companies need capital to build. Higher long-term yields reflect strong demand for money to fund AI data centers, factories, and other projects.
And companies are earning more on their investments. We expect Uniform return on assets (“ROA”) across the entire market to climb from 12% in 2025 to 14% this year and 17% in 2027.
That said, there are two signals to watch for, as both serve as early warnings that this cycle is weakening and high rates are negatively impacting the economy.
If the curve starts steepening because short-term rates fall or if C&I loan growth rolls over. For now, neither of those things is happening.
Rising rates tend to get treated as bad news across the board. The reason behind the move matters more than the move itself.
When the Fed is slashing short-term rates to prop up a weakening economy, a steeper curve is a distress signal. When long-term yields rise because businesses are competing for capital, it’s a sign of an economy that’s growing.
Banks are earning wider spreads and lending more. Businesses are borrowing to expand and corporate returns are on track to climb over the next two years.
None of this means rates can climb forever without consequences. Eventually, expensive money will slow things down. But the bond market indicates the economy isn’t at that stage yet.
Best regards,
Joel Litman & Rob Spivey
Chief Investment Officer &
Director of Research
at Valens Research
Today’s analysis only scratches the surface of what we share with our FA Alpha Members. If you want to gain an in-depth analysis of market trends and uncover undervalued stocks, become an FA Alpha Member today.