Kevin Warsh recently did something the Federal Reserve hadn’t done in more than three years.
On September 16, the Fed unanimously raised interest rates by 0.25%, bringing its target range to 3.75% to 4%.
Investors typically react negatively to such monetary tightening. Higher rates make mortgages, corporate debt, and other financing more expensive.
Rate hikes also increase returns on bonds and cash which can make equities look less attractive by comparison.
However, the market has rallied 2% since the announcement. That’s because there’s another part to this story.
Warsh didn’t raise rates because the economy is falling apart. If anything, his own “economic dashboard” shows the opposite.
A few weeks before the Fed meeting, Warsh laid out the indicators he relies on most to measure the economy’s health. Corporate investment, earnings, credit, and inflation.
Outside of inflation, the economy looks healthy.
Start with corporate investment. Warsh pays close attention to how much businesses spend on equipment, technology, and other long-lived assets. Those are the assets that lay the groundwork for future growth.
Nonresidential fixed investment (essentially business spending on things like buildings, equipment, software, and other productive assets) grew at an 8.5% annualized pace in the second quarter.
Over the past four quarters, investment in equipment and intellectual property has grown around 9%, the fastest pace since 2023. Warsh estimates more than half of this year’s capital spending growth is tied to the AI build-out.
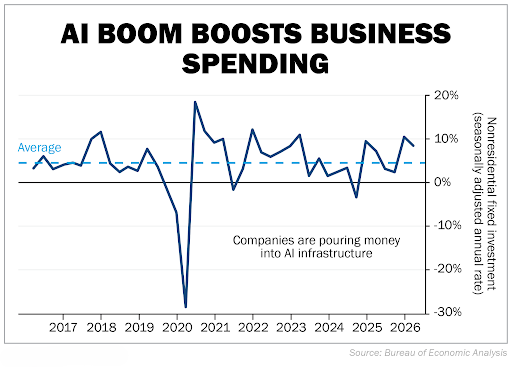
Corporate America doesn’t spend that much when it expects the economy to roll over.
Meanwhile, profits and credit are flashing green. Corporate profits are holding up. After-tax corporate profit margins reached 19.4% in the second quarter, the highest level since the 1940s.
Warsh also noted that S&P 500 Index profits have grown more than 20% over the past year.
Credit tells the same story.
Warsh specifically highlighted the Senior Loan Officer Opinion Survey (“SLOOS”). It’s a quarterly survey that asks bank loan officers whether they’re making it harder or easier for businesses to borrow.
Right now, banks are reporting easier commercial and industrial (“C&I”) lending standards relative to historical trends.
Companies are taking advantage of that access to credit. C&I lending is now growing around 10% year over year.
This leaves us with the only red light on Warsh’s dashboard: Inflation.
The Fed’s preferred inflation measure is the Personal Consumption Expenditures price index. In July, core inflation was still running at 3.3% year over year, well above the Fed’s 2% goal. More than half of the goods and services in the index were still seeing price increases above 3%.
That’s the problem Warsh is trying to solve. A strong economy gave him room to hike rates without doing serious damage. And he can keep leaning against inflation without immediately having to rescue the rest of the economy.
That said, investors are still preparing for the possibility of additional hikes. But the Fed now has a reason to wait and see whether this first hike does the job or not.
If inflation starts cooling while investment, earnings, and credit remain healthy, there’s little reason to rush into another move.
Said simply, the most recent rate hike is a sign of economic strength, not weakness.
For investors, the rate hike is a new risk worth watching. But so far, it hasn’t changed the economic cycle underneath the market.
Companies are still investing, banks are still lending, and earnings are still climbing.
The Fed isn’t slamming the brakes on a fragile economy. It’s tapping them on one that’s running hot. That’s why it’s best to keep an eye on inflation over the next few months.
If it starts to cool, that means the Fed can step back on hiking rates while the strong fundamentals underneath will be free to drive stocks higher.
The headlines focus on the hike itself. But the real story is what’s happening underneath.
Businesses are pouring enormous amounts of capital into the AI build-out. Profit margins are near historic highs. Meanwhile, banks are happy to fund the expansion.
A quarter-point rate hike isn’t going to stop companies that are racing to build data centers, chip factories, and power infrastructure. These are multi-year commitments, and the companies making them expect the returns to far outweigh a slightly higher cost of borrowing.
Warsh raised rates because inflation remains stubborn. But his own dashboard says the rest of the economy is holding up just fine.
Best regards,
Joel Litman & Rob Spivey
Chief Investment Officer &
Director of Research
at Valens Research
Today’s analysis only scratches the surface of what we share with our FA Alpha Members. If you want to gain an in-depth analysis of market trends and uncover undervalued stocks, become an FA Alpha Member today.