America’s industrial revival has been largely spurred by AI.
Every newly built data center requires servers, cooling systems, backup generators, electrical equipment, and miles of supporting infrastructure. And the demand for each of those components flows into supply chains with deep ties to American manufacturers.
But industrials’ momentum is speeding up for reasons other than AI, too. Large manufacturers like GE Aerospace (GE) and 3M (MMM) both crushed their earnings expectations in the recent second quarter thanks to much-stronger-than-expected demand.
This rebound is pushing ahead despite higher trade barriers, persistent inflation, and an energy-price shock tied to the ongoing Iran conflict.
But the strongest manufacturing cycle in years is running into competition for a vital resource: electricity.
Factories need a lot of it and data centers need even more of it. The power supply is struggling to keep pace amid the growing AI build-out.
In other words, electricity has become the decisive constraint in America’s manufacturing boom, and how that bottleneck will shape the next wave of industrial winners.
The manufacturing recovery began earlier this year.
The Institute for Supply Management’s manufacturing index has remained above 50 for six consecutive months. That means the manufacturing sector is expanding. The State Street Industrial Select Sector SPDR Fund (XLI) is up nearly 20% year-to-date, reflecting the broad strength across the sector.
As mentioned earlier, major manufacturers have had a strong year: 3M recently reported its best earnings performance in 19 quarters, and GE Aerospace increased its first-half revenue by 27%, while its order backlog jumped 49%.
Broadly, private investment in industrial equipment has now posted annual growth above 10% for three straight quarters for the first time since 2012.
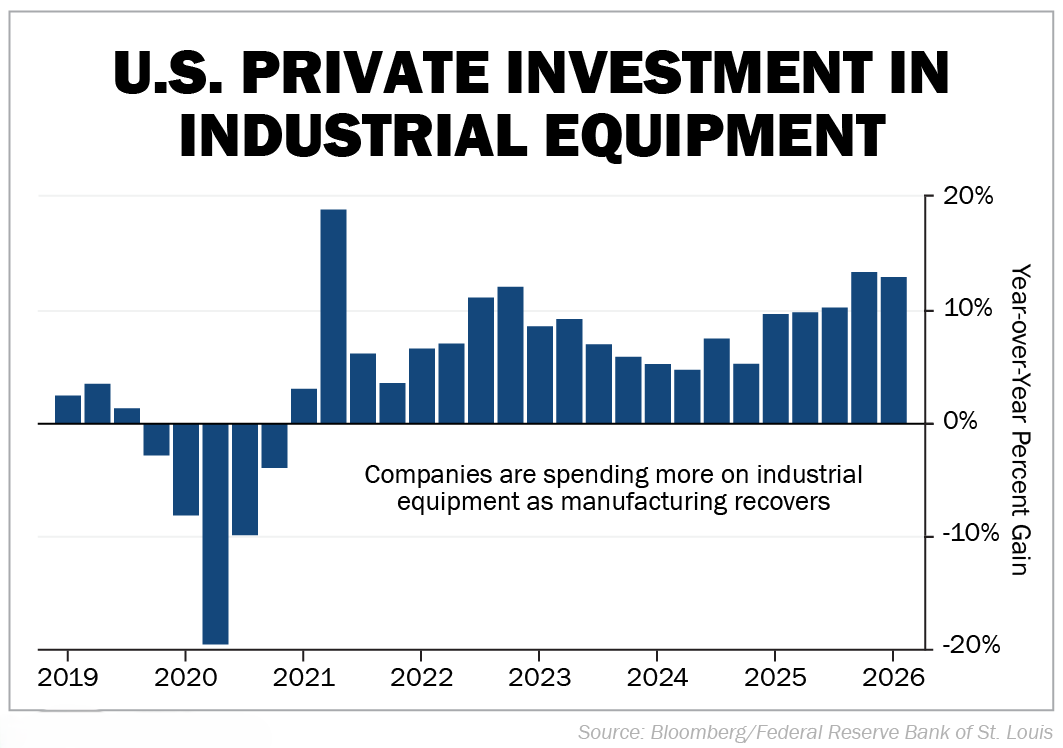
The April 2021 surge in industrials investing reflected a sharp rebound from the pandemic-era trough a year earlier. The growth cooled off but eventually peaked again around 12% in October 2022, before higher interest rates slowed the sector’s growth.
Over the past two quarters, equipment spending has climbed back toward 13% annual growth.
Companies are putting money into equipment for various areas, including information-processing and industrial machinery.
This is to strengthen domestic supply chains and raise productivity. AI is accelerating those changes because of how much physical infrastructure it requires.
The conflict with Iran has added another source of equipment demand. Higher energy prices help utilities and independent producers fund their investments in power generation and grid infrastructure as they race to meet surging electricity demand.
The appetite to build is clear. But without more power, it won’t last for much longer.
Manufacturing investment is concentrated in regions with available workers and low-cost power. But both of those are becoming scarcer.
From 2014 to 2023, the electricity generated by major utilities was essentially flat. Demand grew just 1.2% from 2014 to 2019 alone. Generation finally broke out of that trend in 2024, rising 3% year over year.
That modest pace leaves little room for a surge in data-center demand and factory construction.
Every one of those projects eventually reaches the same bottleneck: a dependable connection to the grid.
The next industrial winners will be those with reliable electricity. Companies are reshoring manufacturing and rebuilding energy infrastructure. The power grid will determine how far that expansion goes.
That puts the major energy players at the center of the industrial renaissance. including power producers, turbine manufacturers, electrical-equipment suppliers, grid contractors, and energy-infrastructure companies.
Companies that move electricity across the grid and help factories secure reliable power will have backlogs for years. And this means investors should focus on businesses that expand power generation.
Best regards,
Joel Litman & Rob Spivey
Chief Investment Officer &
Director of Research
at Valens Research
Today’s analysis only scratches the surface of what we share with our FA Alpha Members. If you want to gain an in-depth analysis of market trends and uncover undervalued stocks, become an FA Alpha Member today.